
DataSolmu blog
ESG reporting reviews and practical disclosure notes
DataSolmu-authored reviews, learning notes, and practical commentary on sustainability reporting, disclosure practice, evidence quality, and regulatory change.
Blog and news articles are currently published in English while localized product pages are prepared.
-
CSRD Omnibus Timing Without False Comfort
A practical review of how companies should read CSRD timing changes without losing sight of reporting readiness.
-
From ESRS Datapoints to Workable Reporting Tasks
A review of why ESRS datapoints need ownership, evidence, review steps, and practical reporting workflow design.
-
Value-Chain Evidence and the Double Materiality Trail
A learning note on documenting value-chain uncertainty, materiality judgements, supplier evidence, and reporting assumptions.
-
A Pillar 3 ESG Disclosure Change Monitor
A review of why Pillar 3 ESG disclosure work depends on version tracking, template ownership, data readiness, and filing discipline.
-
Interoperability Is Not One Thing
A review of why sustainability reporting frameworks can share evidence without becoming interchangeable.
-
What Early ESRS Reports Can and Cannot Teach
A review of how early ESRS reporting practice can help companies learn without becoming a copy-paste template.
-
IFRS S1 as an Evidence Workflow
A learning note on moving from ISSB adoption headlines and IFRS S1 principles to practical evidence readiness.
-
Climate Evidence Lineage for Transition Metrics
A review of why emissions metrics, financed emissions, and transition claims need clear method, boundary, and evidence lineage.
-
Annual Reports as a Disclosure Pattern Library
A review of what sustainability teams can learn from annual report structure, without treating another company’s report as a template.
-
Sustainability Controls Before Assurance
A review of why sustainability reporting needs control discipline before assurance readiness can be credible.
-
ESG Data Quality Is Decision Risk
A learning note on ESG data trust, ratings, alternative data, automated analysis, and the risk of confident decisions from weak information.
-
A Lighter Reporting Path Still Needs Evidence
A review of why simplified sustainability reporting for SMEs still depends on evidence, ownership, and realistic readiness planning.
-
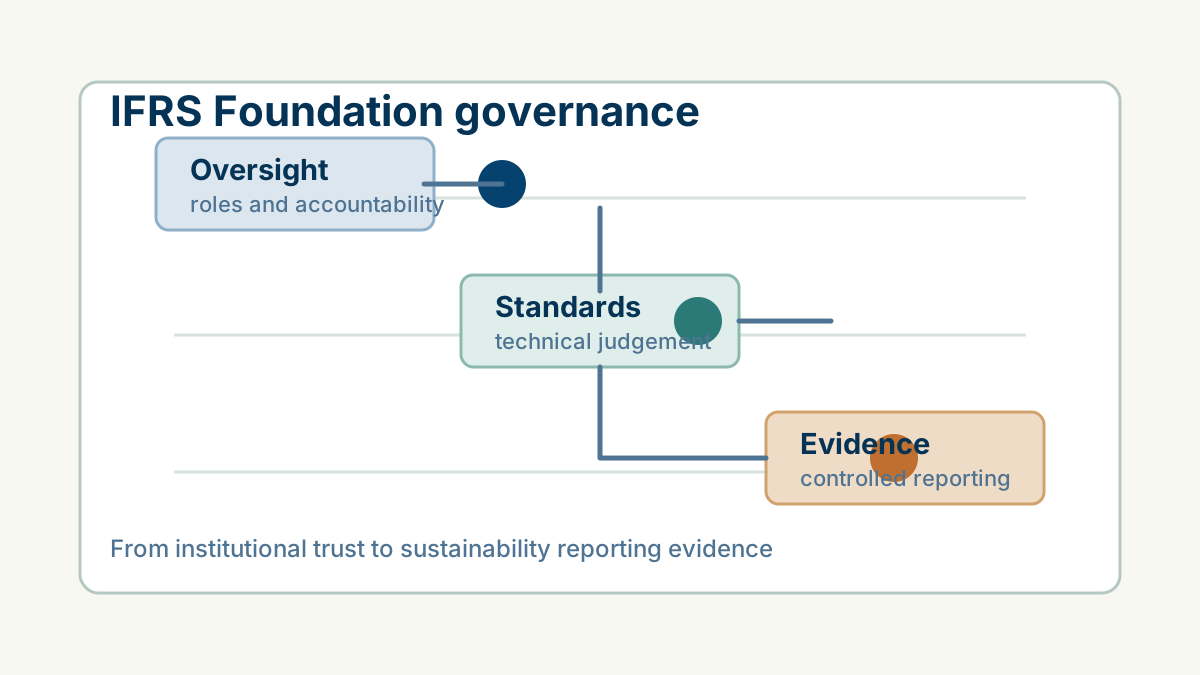
IFRS Foundation Governance as Reporting Evidence
A practical explainer on why standards governance matters for sustainability reporting confidence.
-
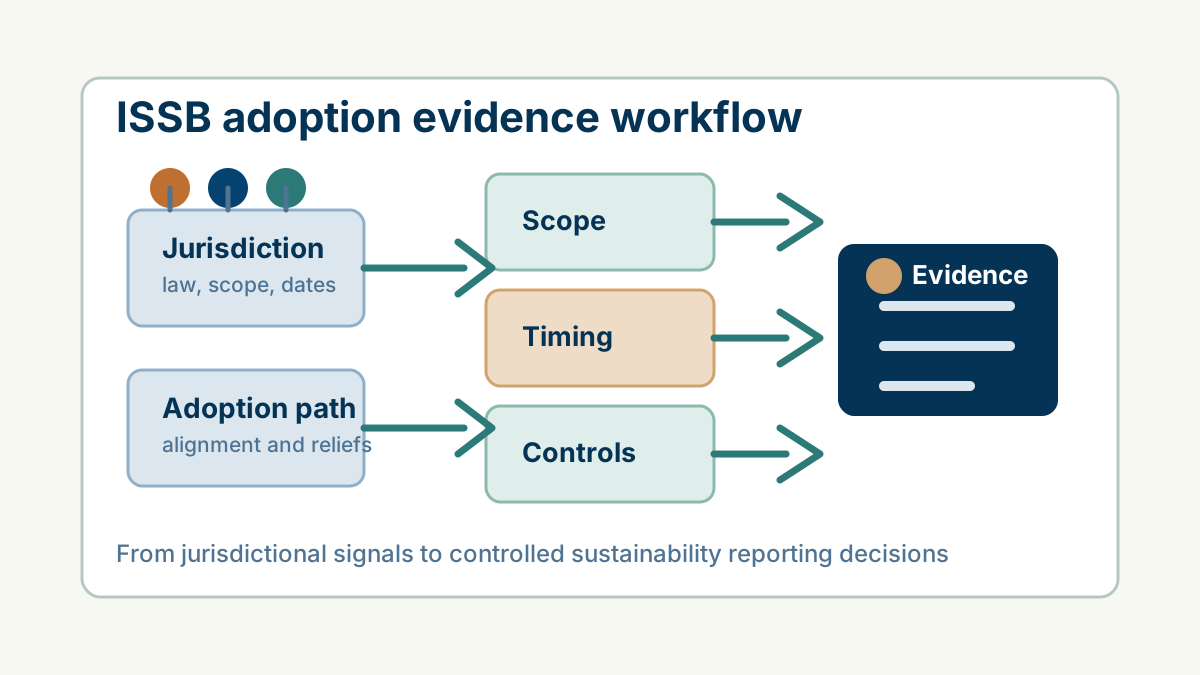
ISSB Jurisdictional Adoption as an Evidence Workflow
How to turn jurisdictional ISSB adoption signals into scope, timing, controls, and evidence decisions.
-
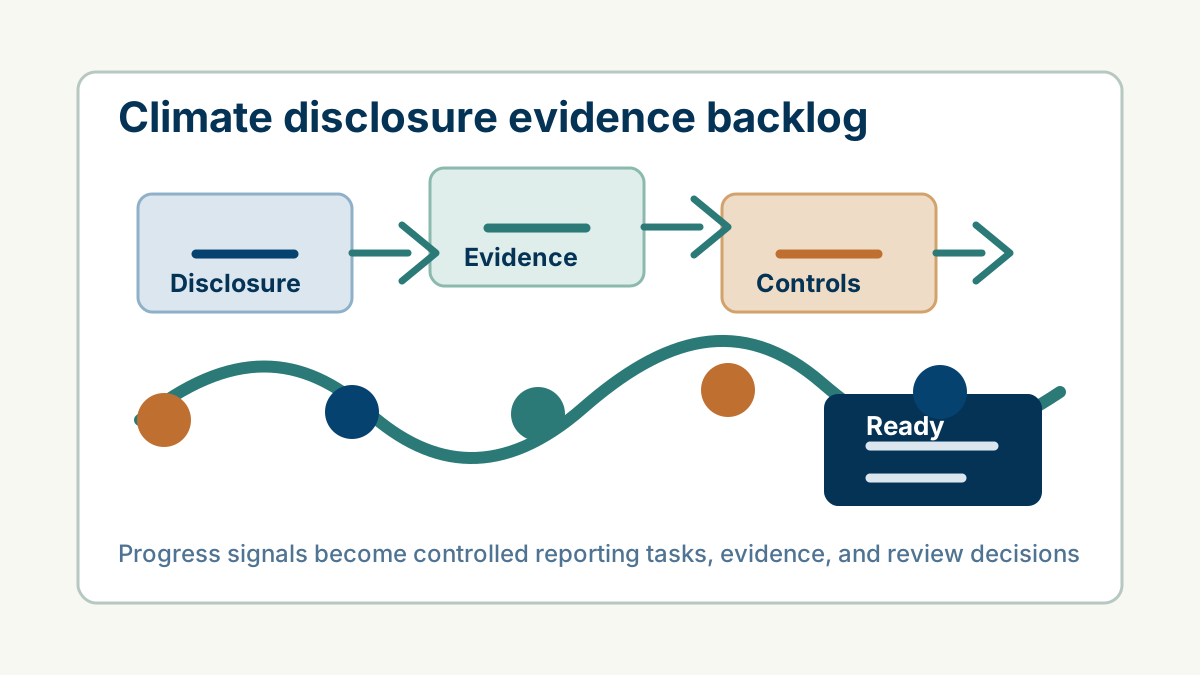
Climate Disclosure Progress Needs an Evidence Backlog
Why climate disclosure progress still needs controlled evidence, transition, and review workflows.
-
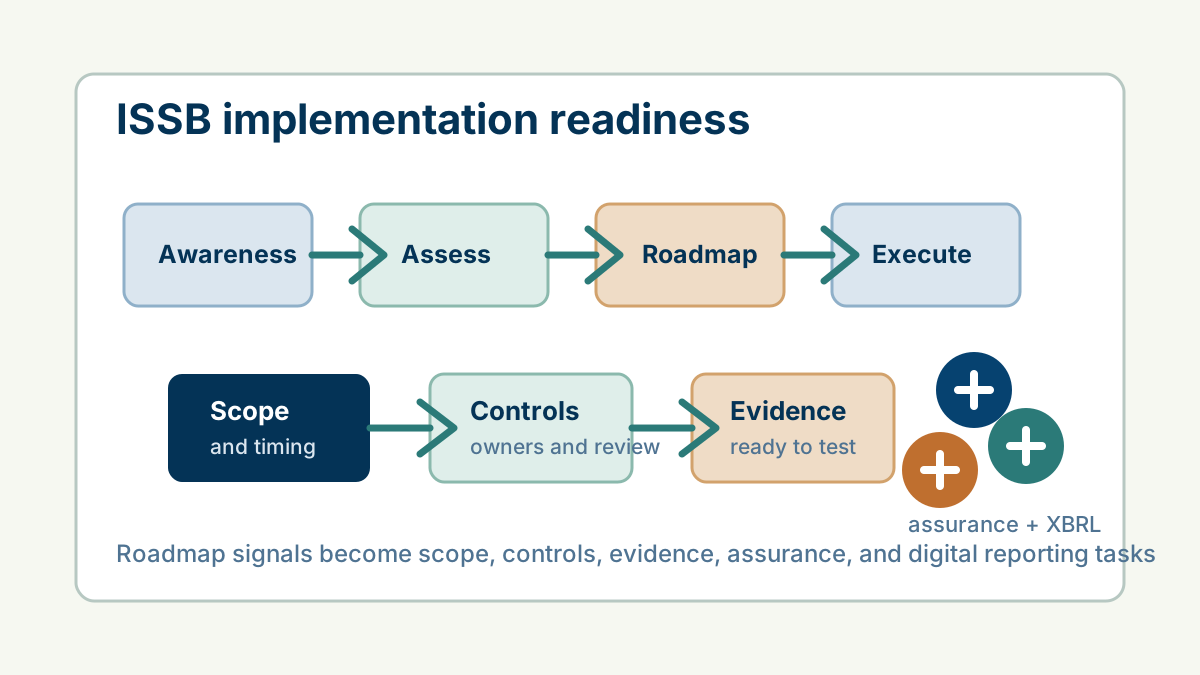
ISSB Regulatory Implementation Needs a Readiness Loop
How ISSB implementation planning becomes scope, readiness, evidence, and review discipline.
-
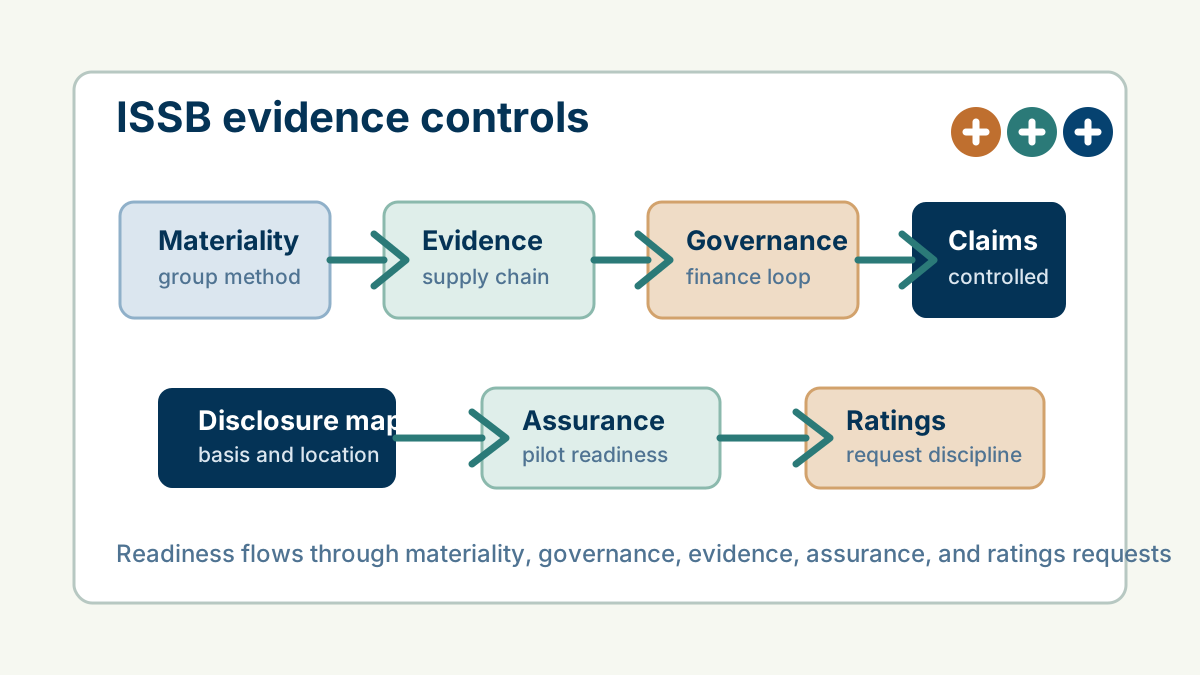
ISSB Readiness Needs Evidence Controls, Not Duplicate Reports
How practical ISSB adoption work becomes materiality, governance, evidence, assurance, and claim-control discipline.
-
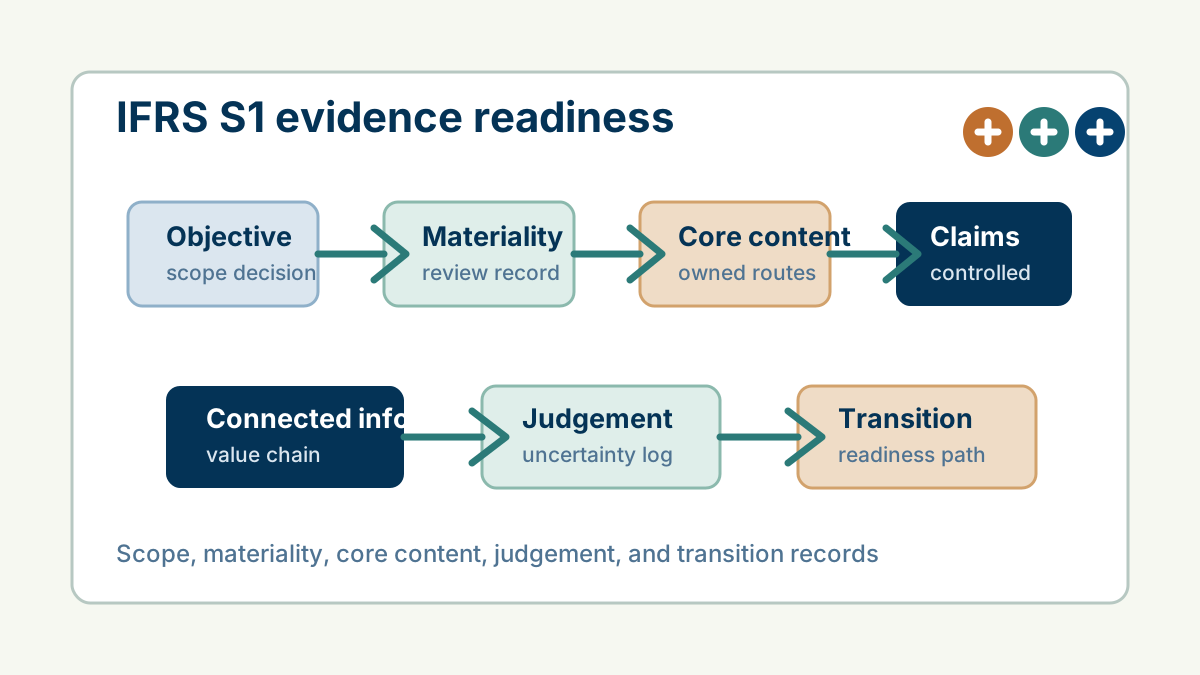
IFRS S1 Basis for Conclusions Makes Evidence Work Visible
How IFRS S1 implementation becomes scope, materiality, core-content, judgement, and transition evidence discipline.
-
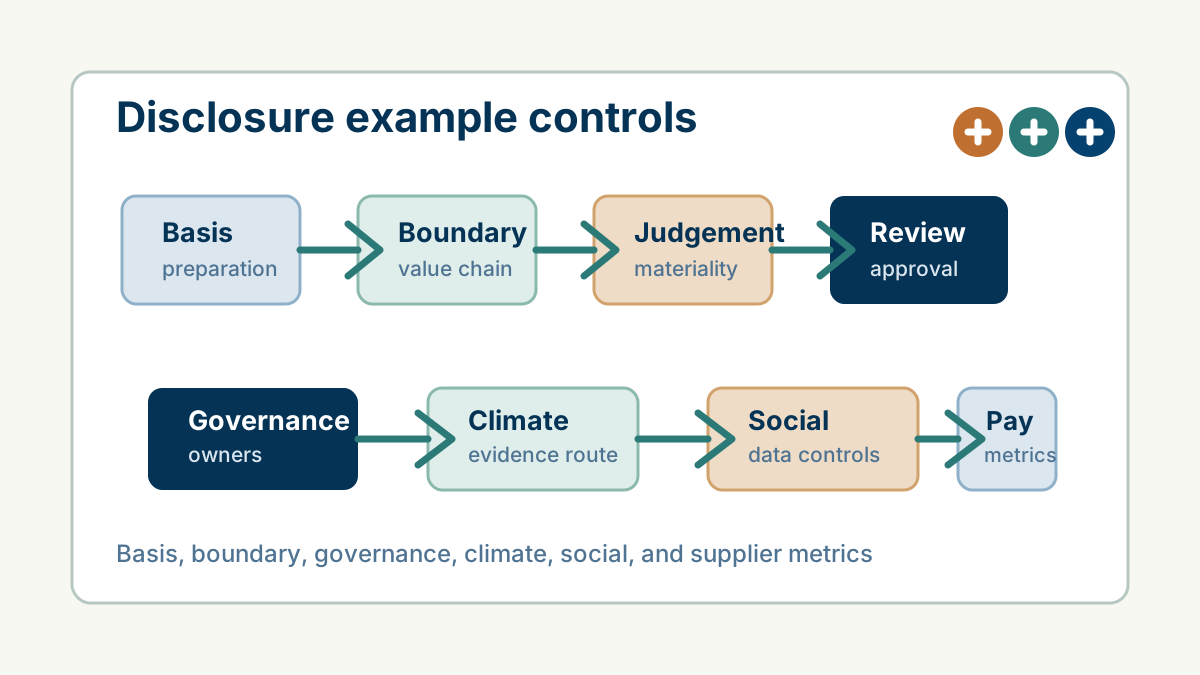
IFRS Sustainability Disclosure Examples Need Controls
How illustrative IFRS S1 and IFRS S2 disclosures become evidence, judgement, governance, and review workflows.
-
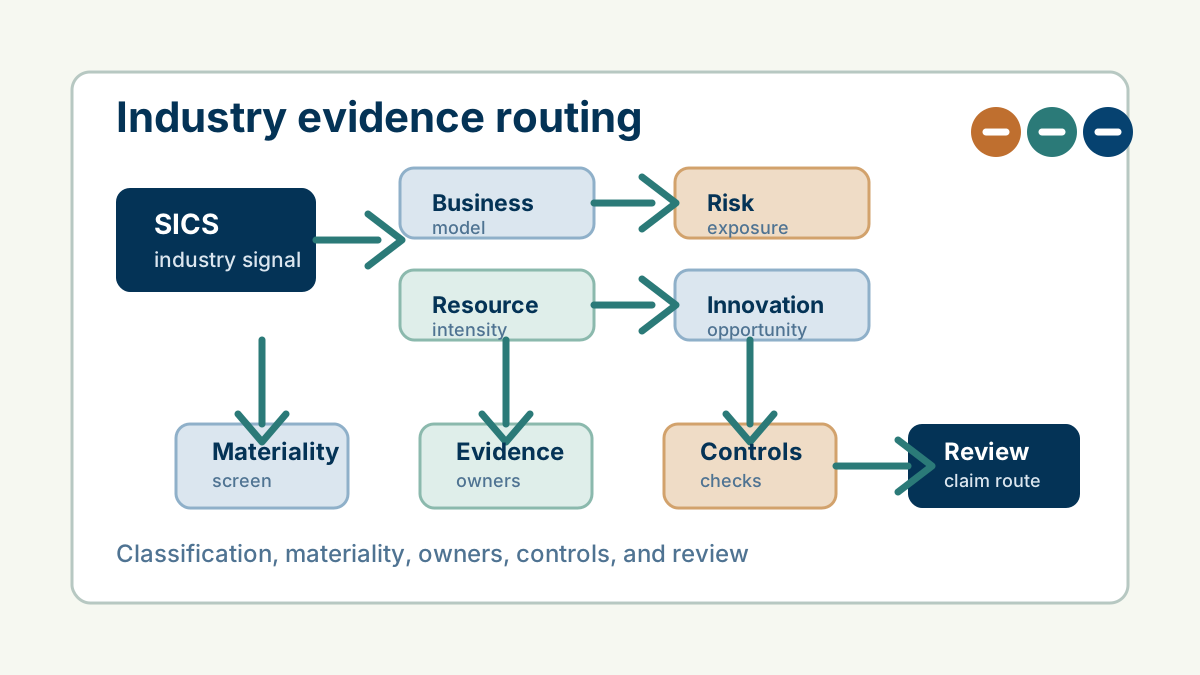
SASB SICS Helps Route Disclosure Evidence
How industry classification can help reporting teams route materiality, evidence ownership, controls, and review work.
-
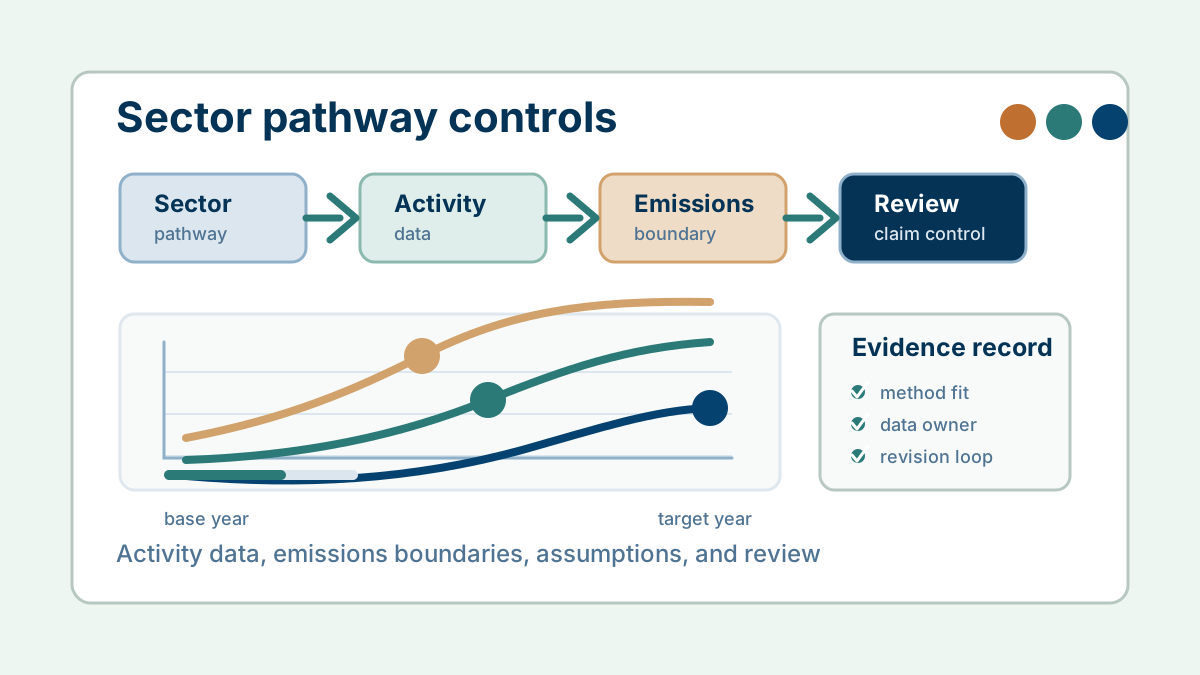
Sectoral Decarbonization Needs Evidence Controls
How SDA-style climate targets turn sector pathways, activity data, emissions boundaries, revisions, and limitations into reviewable evidence work.
-

Turn Reporting Changes Into Evidence Controls
A practical way to turn reporting changes, dependencies, validation, and sign-off into a reviewable evidence trail.
-

Make Disclosure Submissions Reviewable
A practical evidence trail for disclosure sign-off, validation, corrections, and reliable publication.
-

Turn ESG Risk Change Into a Controlled Workflow
A practical way to track ESG risk changes, assign decisions, and retain evidence for reporting readiness.
-

Keep ESRS Datapoint Changes Under Control
A practical way to assess changed ESRS datapoints, keep materiality decisions visible, and protect reporting evidence.
-

Keep Local Impacts Visible in Group Materiality Decisions
A practical evidence trail for connecting subsidiary impacts with group materiality judgements.
-

Keep Additional Sustainability Disclosures Clear
Give each additional disclosure a clear purpose, evidence owner and place in the reporting process.
-

Show What Mitigation Changes in an Impact Assessment
Use timing and evidence to distinguish an environmental impact, an effective response and a future intention.
-

Make Stakeholder Evidence and Threshold Decisions Reviewable
Connect affected stakeholders, impact evidence and threshold reasoning in a materiality decision that can be reviewed.
No blog posts match these filters.